

Trump’s war with Iran is sending oil prices and debt interest rates up. If you follow British politics even at all you will occasionally hear about how the public finances are a mess and this war will only make them worse. But how much of a mess?
There are three obvious stats to compare:
Gilt yields/debt interest rates. This is the rate of interest that is paid for borrowing, I focus on 10-year government debt because I could find the most comparable datasets across countries and time periods.
Debt as a percentage of GDP. This measures how large a country’s debt is relative to the size of its economy.
The budget surplus or deficit as a percentage of GDP.
How worried you should be about any of these stats depends on the other two, so it is important not to cherry pick one to make a country or a time period look better or worse than it is and they should be considered together.Paying high interest rates is never ideal. But it matters much more if a country already has a large and growing debt. High interest rates on a small and shrinking debt are far less problematic.After World War Two the UK had a huge Debt to GDP ratio. But we also had a large surplus and high growth meaning it was falling rapidly and low debt interest rates meant total interest payments were small.
But what to compare to? The obvious comparators are to the UK’s own history and to other developed countries. However, I think both of these categories are too broad. After WWII the UK pursued many policies that it just couldn’t today. It was very difficult for ordinary people to convert pounds into other currencies and we had loans (technically known as ‘sterling balances) from our Empire, Commonwealth and trading partners at far below market interest rates. Therefore I have focused on more recent history, firmly post empire and post free floating exchange rates. I have compared UK public finances today to UK public finances on the eve of various recessions and crises.
For comparing internationally, comparing to our nearest neighbours makes sense. These countries are similar enough to the UK to make comparison meaningful, but follow a wide enough range of economic and foreign policies that there is plenty of scope for variety. Learning that the UK’s position is very different to Singapore’s or the United States would not be that illuminating. Comparing the UK with countries such as Germany or the Netherlands is more informative.
The UK public finances compared to our neighbours
The UK’s public finances are worse than most of our European neighbours. The only countries that are in similarly poor shape are France and Belgium. They are more indebted and piling up debt faster than the UK, but are likely protected somewhat from the full economic consequences of that by their membership of the Euro, hence paying lower interest rates than the UK. The only country with a comparable borrowing rate is Norway, another non-EU country. But Norway also have a sovereign wealth fund worth 4 times the country’s annual GDP that earned a 15% return in 2025. They could likely pay that debt off very quickly if they had to in a crisis.
UK in historical context
The UK’s debt and deficit position is worse today than it was before previous economic shocks. However the interest rate situation is far better than it was prior to some earlier crises.
These facts are not unrelated. In eras when interest rates on government debt above 10% were common, a crisis in government finances would be hit at much lower debt to gdp ratios than our current ones. There has been a global trend to lower interests that the UK benefits from. However, these low interest rates have enabled us to pile up much more debt. We then become very sensitive to increases in the interest rate. That can result from poor decision making from British politicians, or from international events shifting global interest rates higher, or as we have seen recently, both.
This might get worse in the short run
Since Trump’s war with Iran interest rates have gone up almost everywhere.
But the UK is worse hit in North West Europe. While other policy factors including our exposure to global fossil fuel prices and our refusal to exploit all of our oil and gas reserves weakens our position, this is likely mostly a judgement of markets that given our finances and our political class we are the least well equipped to deal with this shock.
There is no sign this will get better in the medium term
There is little cause for optimism. The government does not plan to stop borrowing at any point during this parliament. To the extent that it plans to reduce the deficit, much of the adjustment is backloaded. It relies on tax rises scheduled for the year before the next election and on further tax increases and spending cuts in the financial year after this parliament, which the current government may never have to implement.
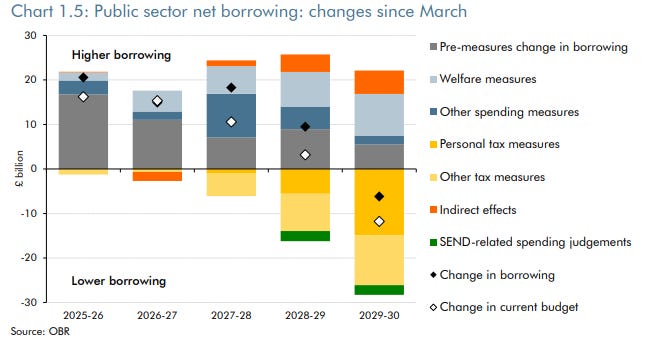
Recent political events also raise doubts about how durable these plans are. On disability benefits, farmers’ inheritance tax and winter fuel payments the government has already shown a willingness to reverse course on tax rises and spending cuts when policies prove politically difficult. It would also be surprising if planned tax rises such as increases in fuel duty were implemented in full.
Nevertheless, financial markets appear to believe that any near term change of government will be for the worse. Mere rumours that Rachel Reeves might be moved from her position as Chancellor were enough to briefly push up government borrowing costs last year. Some Labour figures have suggested that political priorities should focus more on household finances than on the concerns of bond markets. However, countries with debts approaching £3 trillion do not have the luxury of ignoring their creditors opinions.
Lord give me fiscal probity, but not yet
Since Harold McMillan became Prime Minister in 1957 there have been a grand total of 5 fiscal years where Britain has run a surplus (1969-70, 1970-71, 1988-9, 1999-00 and 2000-01). Our debt as a percentage of GDP though has remained stable or even decreased quite sharply on multiple occasions during this period. That’s because of economic growth. During Margaret Thatcher’s time as Prime Minister there was just one year of surplus, but debt as a percentage of GDP almost halved, because GDP got bigger. New Labour often borrowed quite large amounts of money, but they were able to keep debt to GDP relatively stable until the Great Recession because the economy was growing quickly.
Ultimately I do not think our politicians are about to discover the benefits of fiscal probity any time soon. The risk is that means we get out of this mess by printing money and making our living standards worse through high inflation. Assuming that the Iran War is short and the UK is not cut adrift by markets just yet, 2-3% growth sustained for 5-10 years would go a long way to making this situation much more manageable.
Well that's cheered me up.
Inflation is our only escape route. That or default, but why default when you can print money?